Mastering Your VA Loan: Eligibility, COEs, and Homeownership Benefits
Understanding Your VA Loan Eligibility
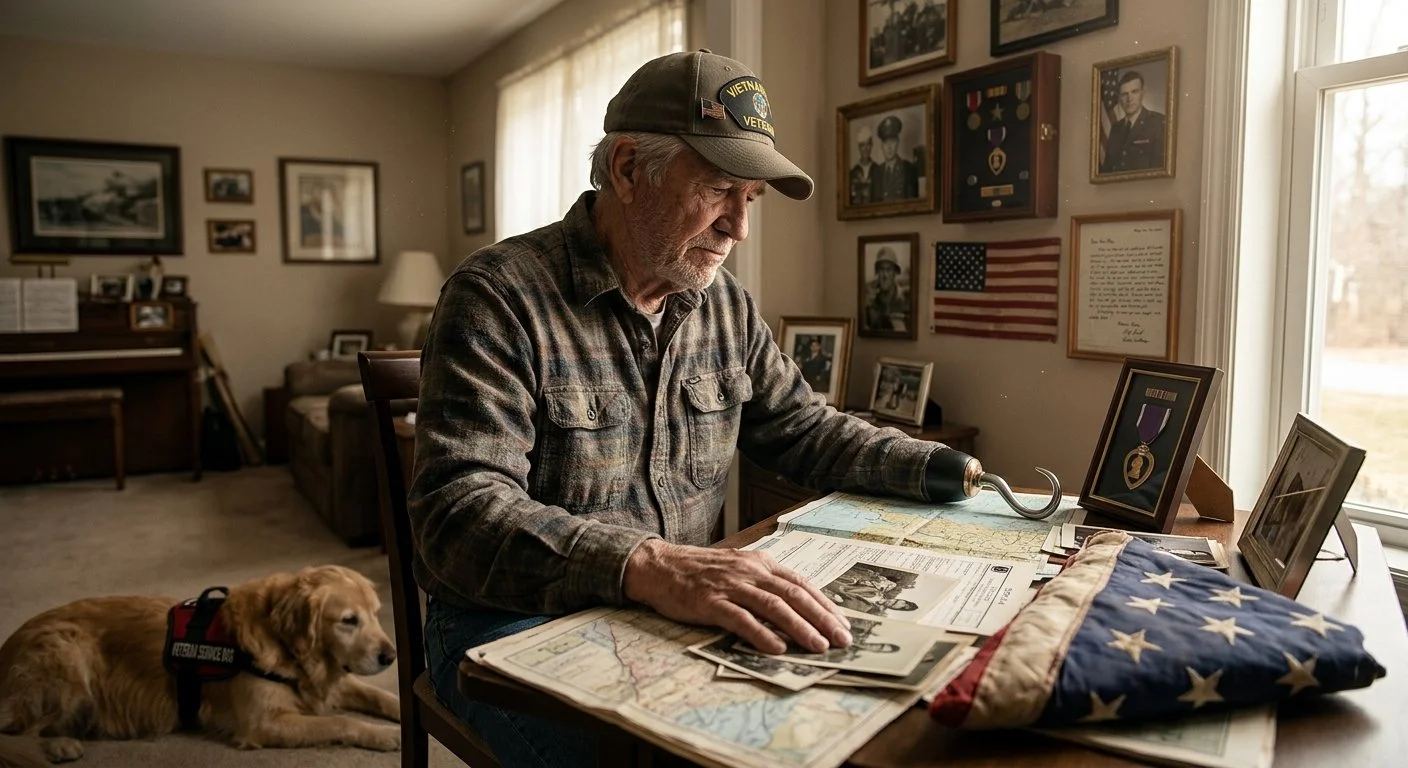
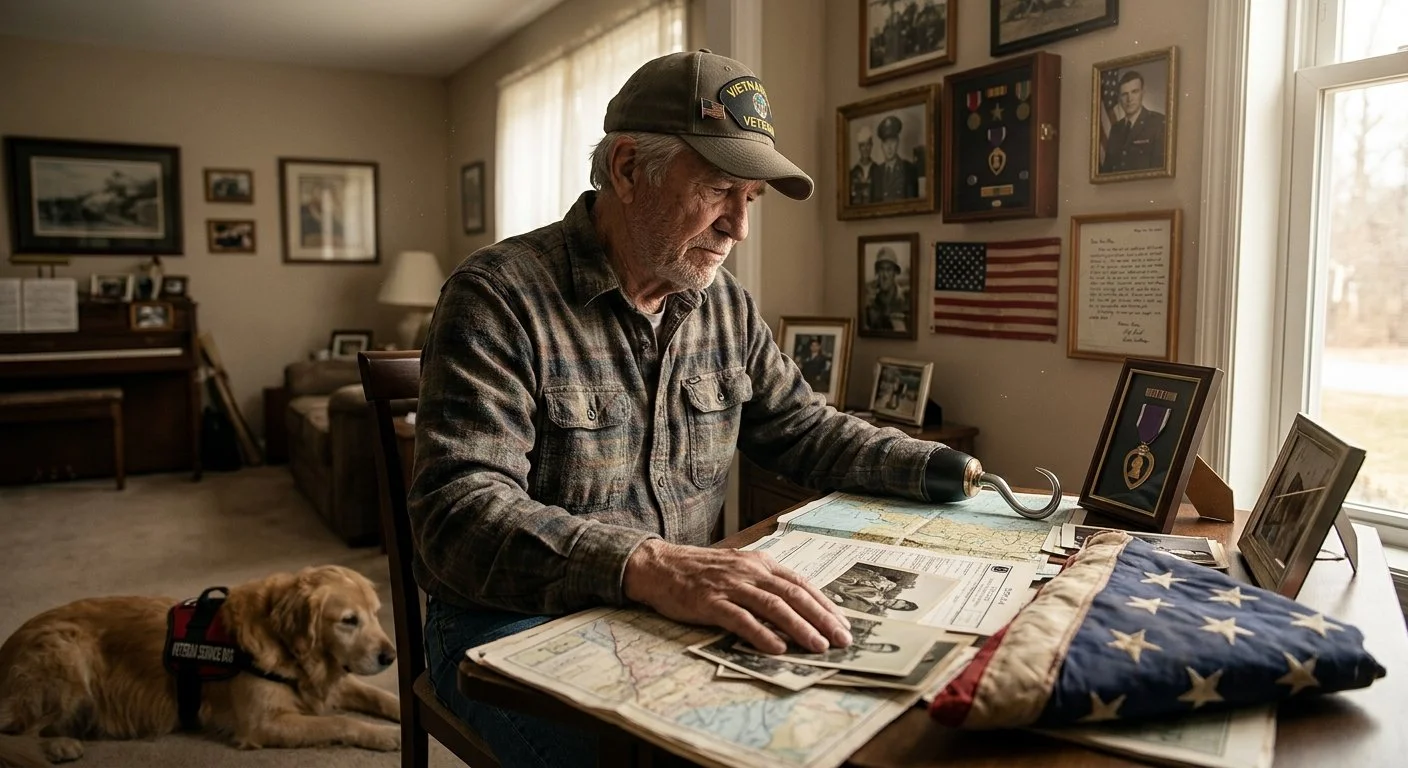
Your qualification for the VA Home Loan program is a lifelong benefit based on your service duration, duty status, and character of discharge, regardless of how many years have passed since you left the military. Veterans who served at least 90 consecutive active-duty days during wartime or 181 active-duty days during peacetime qualify, as do National Guard and Reserve members who completed six years of service or spent at least 90 days on active duty with 30 consecutive days under Title 10 or Title 32 orders. Surviving spouses of service members who died in the line of duty or from a service-connected disability are also fully eligible. Even if you served less than the standard timeframe, a discharge resulting from a service-connected disability typically secures your full entitlement, ensuring that your military dedication translates directly into lasting homebuying power.
Obtaining Your Certificate of Eligibility
The Certificate of Eligibility (COE) is the formal document from the Department of Veterans Affairs that verifies your service history to lenders and details the specific amount of home loan entitlement available for your purchase. While you can obtain a COE on your own by uploading your DD-214 or Statement of Service to VA.gov or mailing VA Form 26-1880 directly to the VA, working with a specialized mortgage broker offers the fastest path. Brokers access the VA’s automated WebLGY portal, which allows us to pull your COE electronically in just minutes using basic personal details. If you lack your DD-214 or service records, a dedicated broker can assist in filing the necessary requests to retrieve your official documents from the National Archives, preventing paperwork delays from stalling your home buying plans.
Maximizing Your Homeownership Advantages
Securing your COE gives you access to mortgage terms that significantly outperform standard conventional and FHA financing options across the board. The VA loan allows eligible borrowers to purchase a home with zero down payment while eliminating the ongoing burden of monthly Private Mortgage Insurance (PMI), which saves homebuyers hundreds of dollars in monthly out-of-pocket costs. Additionally, VA financing features competitive interest rates, capped closing fees, lenient credit and debt-to-income requirements, and reusable lifetime entitlement that can be applied to future primary residence purchases. Partnering with a broker who specializes in VA transactions ensures every step of the underwriting, document gathering, and home purchase journey runs smoothly from initial pre-approval to closing day.
Check out our latest Blog Posts